NSE News - Latest Corporate Announcements

Tuesday, July 24, 2012

Inflation and Growth: Hindu rate of growth?

Inflation is increase in price of goods and services and something to be avoided.. surprisingly inflation at 2-3% is something every nation's central banker aspires for as an ideal inflation target??
Coincidentally the "Hindu rate of Growth" once famous as the rate at which the Indian economy was growing was also 3%

A farmer takes a handfull of seeds worth maybe 1000/= Adds water and fertilizer of say 2000/= and generates goods worth 10,000 in 4-5 months time frame. Farming is not considered as a profitable venture.. when anything that returns 16% ROCE is actually a great thing? why is farming not profitable?

Why is increase in price of food ... food inflation negative while increase in asset prices (house/real estate/stocks) considered positive? Inflation and Growth definition have been force fed .. where "inflation is bad while "Growth" is good when the fact is without "Inflation" there is no growth?

Financial Assets are given higher weightage while core assets such as production of food crops and cotton are labelled as commodities and almost pushed out of the economic picture.. to the level where one is considered a developed country because the economy is basically "Service oriented" 

The Peak Energy crisis which basically means that "Energy is no longer Cheap" changes the priority 180Degrees.. 
Cheap energy prices encouraged "Use and Throw" Replacement mentality..
High energy prices will question if we really need to "Replace" something that is not broken?
Cutting edge was a requirement to stay ahead of competition .. but going forward is it going to be "Live and let live" everybody manages their share of the global consumer market?
Economic growth will tumble (actually negative) while what will remain is basic necessities such as food, clothing and shelter.. with food being the prime economic engine (as its perishable and required on a daily basis) while "Clothing and Shelter" due to their longer shelf life will be smaller part of the future economy..

India has been an energy deprived state and has imported most of its energy requirements.. The original idea was to have an economy that was self sustained which meant "curtail energy demand" (Oil import)
The India of today has allowed the consumer demand to be "open" which is equivalent to taking a child to a toy shop and asking him/her to "Feel free" to buy anything and everything you want.. what we will end up with is a toy shop in our home. Every household has a pvt vehicle (2 or 4 wheels) People go for a "Drive" to kill boredom.. Drive makes people feel productive (I am going somewhere!!) Cars are being marketed as "The First home where I relax"  - Amazingly Nuts!!

What we need is a controlled /directed use of resources to productive assets..Energy Independence is "Key" Renewable energy resources such as hydro electricity must be encouraged. "Telecommute" use public transportation (Rail, waterway, road,air) 

The real economic activity of agriculture production (which happens at the farm level) is a small part of the current global economy and hence the "Peak energy" will shrink the "Financial assets" economy running on Cheap oil while the "Real economy will continue to run and maybe expand at 3% level..

Service industry is a dying industry.. as demand will remain for the basic necessities .. future is bright in "Food industry", "Renewable Energy" and "Public transportation" 

Stocks in general are a loosing proposition..(due to peak energy making most of the economic activities un-economical)  one has to be stock specific .. I have locked in on "Jayant Agro, GAEL, NHPC and Tata Comm" find your gems.. and focus. 


Sunday, July 22, 2012

GAEL: Alert!! Gujarat Ambuja Exports June 2012 Results

Gujarat Ambuja Exports results are out.
ParticularsQuarter Ended
�Jun. 2012Jun. 2011% Var.
Sales553.50367.3151
OPM %8.708.305
PBDT43.0927.6256
PBT34.9320.0774
NP26.7115.2275
So we could expect Net Profit for full year ended 2013 to be 100Cr .. expect the stock to jump on monday July 23,2012

Thursday, July 12, 2012

Jayant Agro: Castor oil Shoes by Nike!!

In the name of environmental concern Nike!! is also making shoes with Castor oil derivatives.. 
unfortunately nobody publishes the real reason.. new EU Regulations (REACH) which would force companies to label their products as carcinogenic or can cause birth defects.. 

Good news for investors in Jayant agro Organics the largest castor seed processing company in India. 
Here is the news for all..

==============

Nike Introduces Sneakers Made Of Beans & Recycled Bottles


The iconic sports brand successfully creates a football shoe that built with sustainability and speed in mind.
Nike has launched the Nike GS in London, a football cleat the company is heralding as the ‘lightest, fastest, most environmentally-friendly production boot the company has ever made.’ The lightweight shoe weighs in at a mere 160 grams and features recycled and renewable materials throughout its body.

The laces, lining and tongue of the shoe are made from a minimum of 70% reused plastics, including recycled water bottles and polyester, and the traction-plate on the shoes is made from 50% renewable Pebax® Renu, a plant-based material composed of 97% castor beans. The result is a shoe that is lighter and stronger for the athlete, and more sustainable for the environment- using the castor beans makes the shoe 15% lighter than traditional cleats while the beans also require much less water to grow than other natural materials. The Nike GS are also chemical free, and the Kangaroo leather in the shoes are made with 35% less carbon emissions than traditional material. Andy Caine, global design director for Nike Football, says of the Nike GS:

The Nike GS is the lightest and fastest football boot we’ve ever made and really defines a new era in how we create, design and produce elite football boots. When you can deliver a boot that combines high end performance and a low environmental footprint that’s a winning proposition for players and planet.

Only 2012 Nike GS shoes were made; they will be available for purchase through Nike.com and selected online retailers for 300 USD beginning August 15th.Nike GS

Link to original article: (Link)

Sunday, July 08, 2012

Song: Johnny cash: One piece at a time and it would'nt cost me a dime

I was working with GM in Detroit .. though nowhere close to an assembly plant for Cadillac.. 
GM cars (higher end) are really good cars .. unlike the image in the mind of Indians in US...
I like this song.. (long before I went to US.. never though I would be working for GM.. made a bunch buying GM Bonds when GM was reorganized in 2009 (Link) )


Well, I left Kentucky back in '49
An' went to Detroit workin' on a 'sembly line
The first year they had me puttin' wheels on cadillacs

Every day I'd watch them beauties roll by
And sometimes I'd hang my head and cry
'Cause I always wanted me one that was long and black.

One day I devised myself a plan
That should be the envy of most any man
I'd sneak it out of there in a lunchbox in my hand
Now gettin' caught meant gettin' fired
But I figured I'd have it all by the time I retired
I'd have me a car worth at least a hundred grand.

[CHORUS]
I'd get it one piece at a time
And it wouldn't cost me a dime
You'll know it's me when I come through your town
I'm gonna ride around in style
I'm gonna drive everybody wild
'Cause I'll have the only one there is a round.

So the very next day when I punched in
With my big lunchbox and with help from my friends
I left that day with a lunch box full of gears
Now, I never considered myself a thief
GM wouldn't miss just one little piece
Especially if I strung it out over several years.

The first day I got me a fuel pump
And the next day I got me an engine and a trunk
Then I got me a transmission and all of the chrome
The little things I could get in my big lunchbox
Like nuts, an' bolts, and all four shocks
But the big stuff we snuck out in my buddy's mobile home.

Now, up to now my plan went all right
'Til we tried to put it all together one night
And that's when we noticed that something was definitely wrong.

The transmission was a '53
And the motor turned out to be a '73
And when we tried to put in the bolts all the holes were gone.

So we drilled it out so that it would fit
And with a little bit of help with an A-daptor kit
We had that engine runnin' just like a song
Now the headlight' was another sight
We had two on the left and one on the right
But when we pulled out the switch all three of 'em come on.

The back end looked kinda funny too
But we put it together and when we got thru
Well, that's when we noticed that we only had one tail-fin
About that time my wife walked out
And I could see in her eyes that she had her doubts
But she opened the door and said "Honey, take me for a spin."

So we drove up town just to get the tags
And I headed her right on down main drag
I could hear everybody laughin' for blocks around
But up there at the court house they didn't laugh
'Cause to type it up it took the whole staff
And when they got through the title weighed sixty pounds.

[CHORUS]
I got it one piece at a time
And it didn't cost me a dime
You'll know it's me when I come through your town
I'm gonna ride around in style
I'm gonna drive everybody wild
'Cause I'll have the only one there is around.

[Spoken] Ugh! Yow, RED RYDER 
This is the COTTON MOUTH
In the PSYCHO-BILLY CADILLAC Come on

Huh, This is the COTTON MOUTH
And negatory on the cost of this mow-chine there RED RYDER
You might say I went right up to the factory
And picked it up, it's cheaper that way
Ugh!, what model is it? 
Well, it's a fortynine, fifty, fifty one, fifty two, fifty three, fifty four, fifty five, fifty six, fifty seven, fifty eight, fifty nine automobile! It's a sixty, sixty one, sixty two, sixty three, sixty four, sixty five, sixty six, sixty seven, sixty eight, sixty nine, seventy automobile


Wednesday, July 04, 2012

Jayant Agro: June DGFT Export numbers

Director General of Foreign Trade has published Export data for Month of June 2012 
as per DGFT data Jayant has Export FOB (Free On Board)for June 2012 at 157.9Cr 
You can get the info at DGFT Website (Link)

License no info for Jayant is available here (Link)
IEC Code for Jayant is: IEC: 0393002047

Here is the processed data (June 2012) for every one..

April 2012 FOB Data was: 242.07Cr (Link)
May 2012 FOB Data is: 187.59Cr(Link)
June 2012 FOB Data is 157.9Cr
So Q1 2013 ie quarter ending June 2012  = 242.07 + 187.59+157.9 = 587.56Cr

Another observation is that higher value Derivatives exports are forming a larger part of Jayant's exports.. Derivatives are higher value exports where the FOB/CIF is around 50 while castor oil & 1st Generation derivatives have a FOB/CIF ratio of 20-30 which is good news for investors in Jayant Agro.

PN: Please Note this is the expected sales numbers to be reported by Jayant Agro based on publicly available information. There is also a possibility that there is misinterpretation of data... Please do your own deep dive before investing

Friday, June 29, 2012

Jayant Agro Organics: May 2012-CIF,FOB Data

Director General of Foreign Trade has published Export data for Month of May 2012 
as per DGFT data Jayant has Export FOB (Free On Board)for May 2012 at 187.59Cr 
You can get the info at DGFT Website (Link)

License no info for Jayant is available here (Link)
IEC Code for Jayant is: IEC: 0393002047

Here is the processed data (May 2012) for every one..


April 2012 FOB Data was: 242.07Cr (Link)
May 2012 FOB Data is: 187.59Cr

PN: This is publicly available information on the internet and there is a possibility of misinterpretation and misrepresentation.. Please do your own deep dive before investing.


Monday, June 18, 2012

Jayant Agro: Swastika Investmart recommends with target price 217.60

Swastika Investmart has recommended a buy on Jayant Agro Organics with starting price as 128 and target price of 217.60 , Duration 9-12 months, Expected return 70%


Pls note standlone results have been considered .. while we generally review consolidated data..
Link to original document (Link) 


=happy investing

Saturday, June 16, 2012

Jayant Agro Organics: Star Trading House, April 2012 FOB Data

According to Director General of Foreign Trade.. Jayant Agro Organics is status holder as "Star Trading House" valid till 2017


Link to original Document: (Link)

A Star Trading House category needs exports of 2500Cr FOB value in current + 3 yrs ie past 4 yrs (Taken together) which translates to about 625Cr each year.. 


We need to look when Jayant enters into Premier Trading house category 1,875Cr exports every year for past 4 yrs..Jayant should reach that in next 3 yrs as we have already crossed 1770Cr in March 2012..

Link to Original Document: (Link)

Jayant Agro Organics has the IEC Code: 0393002047
Now last time the concern was what is the FOB value of exports.. we had the license numbers and  CIF Value.. The DGFT website has the provision where you can enter the License Number and the IEC Code and you can get the FOB Value of the export. 
We already have the facility for determining the License number for Jayant Agro
VKUY and FPS April 2012 (Link)
DEPB April 2012 (Link)

So we can use Jayant Agro Organics  IEC Code (0393002047) and License Number from the above links and get the FOB Value at this Link

So now we can get the FOB value which should translate to sales numbers reported by Jayant 

Now just to get everyone up and running I have collated the FOB data for April 2012 for Jayant Agro Organics here it is.. (You can validate by following the process mentioned above in red)


So as per the DGFT Export license issued in April 2012 Jayant has FOB export sales of 242.07Cr in April 2012..
  PN: As per my communication with Jayant management (for Jan-March 2012 Sales figures) there is a misinterpretation by me of the License and FOB Data issued by DGFT.. (for Jan-March 2012) (comments section of previous post link)

Last post we had discussed about a google search to find the license data.. well DGFT has provided a link where you can get the license data.. (Link)

VKUY and FPS data is under: (Duty Credit Script Link)
DEPB is under DEPB Link)

So no need to google search just go to DEPB website and get the latest data..

PN: These are my personal views/interpretation about publicly available information... please do your own deep dive before investing.


Saturday, June 09, 2012

Jayant Agro Organics: Peek into the future..

Q1 results are nothing but sales and profit for the months of 
April-May June which is reported in "July"

Director General of Foreign Trade (DGFT) publishes India's 

export data every month.. so by July we can get our hands into 
the dgft export numbers for Jayant agro in month of April, May 
and June giving us a fair idea of what the sales number will look 
like in Q1 report in July..

x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x
If you want to find the dgft export numbers for Jayant for a month 

in the past you need to search in google with the keywords 
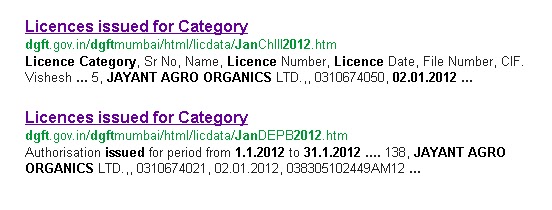
"Licences issued for Category dgft (month) (year) Jayant agro Organics"
Search for Month: Jan year: 2012 will be
=========================
Licences issued for category dgft Jan 2012 Jayant Agro Organics
=========================
The search we are looking for is under the heading "Licences issued for Category"


x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x
There are 3 sections under which Jayant Agro Organics reports 
export data..
- Vishesh Krishi Upaj Yojana
- Focus Product Scheme
- DEPB Post Export
Focus Product Scheme and Vishesh Krishi Upaj Yojana are

 in one link while DEPB Post Export is a separate link..


So for each month's export data we need to collate data from two 
links provided by DGFT
For the month of Jan 2012 the two links are:-
Vishesh Krishi Upaj Yojana & Focus Product Scheme (Link)
DEPB Export (Link)
x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x
The reported data is CIF (Cost of Insurance & Freight) ..

 it does not disclose the actual value of export which 
is reported as FOB (Freight on Board)

Luckily I did get my hands on FOB Data from dgft which was 

available to public for Feb and March 2012 and compared 
CIF and FOB ratio.. According to me..for Jayant 
FOB is approximately 30 times CIF for Vishesh Krishi Upaj Yojana
FOB is approximately 50 times CIF for Focus Product Scheme
FOB is approximately 30 times CIF for DEPB Export 
(I did not have the FOB data for DEPB Export .. its my 
own assumption)


Right now you can peek into Jayant Agro's  CIF data for April 
2012 just Google search for:-
x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x
Licences issued for category dgft April 2012 Jayant Agro Organics
x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x-x
remember there are two links from which you need to collate 
the data..


PN: I did speak to the management about the data being published
 by DGFT and my interpretation of sales numbers..
Jayant Agro management's understanding was that I had drawn 
wrong conclusions and hence my estimated sales numbers for 
Jayant are due to mis-interpretation of DGFT data... 


So please understand any information you conclude from DGFT 
data is your own interpretation.. and quite possibly wrong.. Its a 
Peek into the future but not necessarily a true complete picture..


I am long Jayant Agro Organics..


=happy investing


Saturday, June 02, 2012

Gujarat Ambuja Exports: March 2012 Year End Result Review

Gujarat Ambuja Exports reported its year ending March 2012 results on May 21,2012.


1. Year on Year..
- Sales have increased by 8.92%
- Expenditure has increased by 11.77% (Includes Forex loss of 4.34Cr for full year.. Q4 there was a forex profit of 11.23Cr)
- Profit Before Depreciation Interest and Taxes has decreased by 56.65% (Margins have contracted from 7.42% (2011) to 5% (2012) as percentage of sales)
- Interest expenses increased by 66.50%
- Taxes reduced by 56.78%
- Net profit was down 47.18% (PBDIT was down 56.65% and net profit was down only 47.18% so there is a 9.47% +ve difference between PBDIT and Net Profit)

2.  PBDIT Margins have contracted as percentage of sales from 7.42% (2011) to 5% (2012) this is a cause of concern..
- though interest payments have increased by 66.50% (Y-Y) as percentage of sales.. interest payments are less than 1% which is still manageable and due to the managements clear intentions to maintain Zero long term debt levels..
I must add that GAEL is an agro processing major which procures raw material during harvest season when its cheapest.. and then the agro products are further processed during the year. Short term loans are taken from banks during the harvest season and paid backin the next 6-12 months.. Interest rate hike by RBI has impacted GAEL by increasing its interest costs by 66.50% (Y-Y)

3 GAEL has 4 divisions. - cotton yarn, - maize processing, - agro processing, - Windmill
- Cotton yarn division seems to be the culprit.. reporting -26.02cr Net profit(+11.29cr 2011) .. which means cotton yarn division itself has a profit impact of 26.02 + 11.29 = 37.31cr. (Y-o-Y)
- Maize processing division also has had a sharp fall in profits as well as profit margins..
Profit margins:- 12.57% (2011:-20.22%)
Profit impact on 2012 profits is 25.81Cr (Y-o-Y)
The uttarakhand maize processing plant had a tax free period which could have come to an end and hence we are seeing profit margins contract.. so going forward the maize processing division profit margins might remain around 12.57% is my understanding. 
Karnataka plant might get tax breaks.. which could help in increasing margins once again. (Lets hope)
- Agro Processing division has seen its profit margins expand.to 4.24% (March 2011:-3.65%) this had a positive impact on net profit of 12.85Cr (Y-o-Y)
- Wind mill division  has a small but consistent contribution of 4.46Cr.

Current Assets:- 609.38Cr (528.11Cr-2011)
Current Liabilities:- 531.51Cr (431.26Cr-2011)
Net Current Assets:=>>> Current Assets - Current Liabilities =  77.87Cr (96.85Cr-2011)

A drop in "Net Current Assets" indicates that the management has been active in improving capital efficiency by holding back lenders (Increasing Liabilities) and reducing advance payments to creditors (Decreasing Current Assets)
Net Current Assets:- 77.87Cr (96.87Cr-2011) indicates a reduction in working capital requirement even as sales have increased or remained consistent... a big positive.

Conclusion:- GAEL has reported a drop in profits of 47.18% even as sales have remained constant. a dig down indicates.. drop in profits due to Cotton yarn division and margin decrease in maize processing division.. Maize processing division margin drop could be permanent as uttarakhand maize division was enjoying tax incentives which are set to expire(my opinion)...  
Net Current Assets have reduced which indicates the management is in control and taking steps to improve the health of the company.. 
GAEL is doing just fine and accumulating wealth for its investors.. but one must remember the global investment climate is turning out to be long term negative.. my personal opinion is further expansion plans should only be done after careful review.. its best to accumulate financial assets (cash) as some "not so well managed" company assets might be available cheap for taking..


Sunday, May 27, 2012

Jayant Agro : Results Quarter and Year ending March 2012

Jayant Agro Organics
CMP: 119
Market Cap: 178.50Cr


Jayant Agro Year ending March 2012 results are out. lets look at the standalone numbers which are reported in the press..


The results at standalone level is picture perfect. 
Sales (topline) up by 45.17% and Net Profit (Bottomline) up by 52.76% indicating profit margin expansion.

3 year standalone numbers are even more impressive..
March 2010 Sales: 880.33Cr Net Profit: 7.84Cr
March 2011 Sales: 1,148.07Cr Net Profit: 17.74Cr
March 2012 Sales: 1,666.69Cr  Net Profit: 27.10Cr

In 3 yrs sales have doubled while net profits have more than tripple'd !! 

Consolidated Results:-
As mentioned before the numbers that we need to look at is consolidated results because of materially significant subsidiaries of Jayant Agro Organics namely Ihsedu Agro Chem and Ihsedu Specialty Chemicals (Ihsedu Specialities Chemicals is now awaiting merger approval from high court with Jayant Agro Organics)

3 yrs Consolidated Results for Jayant Agro.

1. At the consolidated level year on year sales growth is 51.30% which is great but net profit growth at 12.09% leaves a lot to be desired. the top two y-y highest percentage change are Interest (65.26%) and Taxes (59.01%) 

2. Interest payments: My understanding was that govt was giving a 2% interest rate subsidy to motivate exporters... hence exporters are reporting interest expense to claim that subsidy. 
Interest rate payments at 2.26% of  sales for year end March 2012 seems to be just that.. though a little on the higher side.. needs to be watched closely in the future..

2. Tax payments: Tax payments are up 59% (y-y) while net profit is up just 12% completely baffles me..
One of the many reason's companies are incorporated is because they are effective in reducing the tax paid to govt. 
Increase in tax paid :- 16.91cr (2012) - 10.63cr (2011) = 6.27cr
Increase in net profit :- 27.54cr (2012) - 24.57cr (2011) = 2.97cr

Surely taxes paid in 2012 is on the higher side and net profit is on the lower side.. 
Corporate Income tax rate in India is 33.2% so lets try to calculate the hypothetical PBT and hence Net profit for tax paid of 16.91Cr ..
Tax Paid 16.91Cr 
Effective tax rate 33.2%
PBT: 51.24Cr
Net Profit: 51.24 - 16.91Cr = 34.33Cr
P.N: this is a hypothetical calculation for our own understanding.

Here is another interesting piece of info.. effective taxe rate for Jayant past 3 yrs
2012: Tax paid: 16.91Cr Net Profit: 27.54 PBT: 44.46Cr Effective tax rate: 38% 
2011: Tax paid: 10.63Cr Net Profit: 24.57Cr PBT: 35.21Cr Effective tax rate: 30%
2010: Tax paid: 10.64Cr Net Profit: 12.46Cr PBT: 23.10Cr Effective tax rate: 46%

Jayant it seems has a habit of paying higher taxes.. infact in 2010 and 2011 tax paid is 10.64Cr while net profit is 12.46Cr(2010) and 24.57Cr(2011) 

Conclusion: Jayant year end March 2012 numbers though "impressive"  at standalone levels is just "fair" at consolidated levels mainly because of low rate of net profit growth.. digging a little deeper the taxes paid are very high and seems to give an idea that profits are being watered down.. looking at the last 3 yrs data we can see that Jayant management seems to be conservative in reporting net profit figures and taxes paid 3yrs avg is higher than the 33.2% corporate income tax rate set by govt of India. 
My personal opinion is for the year ended March 2012 at gross level (PBDIT) profit margins are stable  ..which could imply ...Interest rates are over stated and maybe depreciation also .. this has effectively reduced the net profit figures.. and skewed the results to such an extent that tax increase is 6.27cr while profit increase is just 2.97cr..  I would say jayant could have ideally reported march 2012 net profit of 34.33cr 

PN: these are my personal views/interpretation based on publicly available data.. Pls do your own deep dive before investing.

Jayant Agro Blog Archive


Monday, April 30, 2012

5000 Tonnes of castor seed sold by Acazis AG

Gilching, Germany, Mar 19, 2012 (Thomson Reuters ONE via COMTEX) -- Acazis AG / ACAZIS AG signs its first CONTRACT for sale of 5000 tons of castor beans and appoints SINOETH Hong Kong International Group Limited as exclusive distributor for China, Japan, Korea, Ethiopia. . Processed and transmitted by Thomson Reuters ONE. The issuer is solely responsible for the content of this announcement.
Gilching, Munich, 19 March 2012 - Acazis AG based in Gilching, Munich signed a 5 year agreement with Sinoeth Hong-Kong International Group Limited on 15 March 2012. The agreement foresees the marketing and sale of all or part of Acazis AG's castor harvest. It will be renewed for a further five years should neither party decide to terminate the contract.
Sinoeth Hong Kong has committed to purchasing from Acazis AG, a minimum of 1000 tons of castor beans annually. The purchase price of the castor beans is based on the official prices indicated by the Indian Commodity Futures Exchange NCDEX (www.ncdex.com/MarketData/SpotPrice.aspx ) in India. At present the SPOT price for one ton of castor beans corresponds to approximately USD 720, -.
Sinoeth Hong Kong has excellent commercial contacts in both in Asia and beyond. Some of the companies with which Sinoeth Hong Kong currently collaborates include the following:
SDIC International Trade Co. Ltd.,
China National Light Industrial Products Imp. & Exp, Corporation,
China Star Int. Trade Co. Ltd.,
SinoTruk (Hongkong) Ltd.
Sandong Wuzheng Co. Ltd,
Quingdao Doublestar Tire Co. Ltd.,
Changzhou Dongfeng Agriultural Machinery Group Co. Ltd. and
JiangSu Sevencontinent Green Chemical Co. Ltd.
The terms and conditions agreed with Sinoeth Hong Kong already include the purchase of a minimum of 1000 tons of castor beans in 2012. Acazis has guaranteed delivery of the castor crop in two instalments - September and December of this year.
Patrick Bigger, CEO of Acazis AG, has expressed great pleasure in the company's partnership with Sinoeth Hong Kong. He states; "The signing of such a long-term contract with Sinoeth Hong Kong has opened the market for Acazis AG in the sale of castor in the Asian and, in particular, the large Chinese castor market. The conditions relating to a minimum annual purchase provide us with greater operational planning guarantees whilst at the same time minimising the risks for Acazis AG.
We are convinced that we have found in Hong Kong Sinoeth an experienced and very well-connected trading partner which will facilitate access to the world's most important castor importers. With this in mind, we very much look forward to both a fruitful and long-term cooperation."
Jason Xie, CEO of Sinoeth Hong Kong adds; "The contract signed with Acazis AG means that we have acquired one of the major producers of castor oil in the future for our customers in China and Asia. The long-term contract term of 5 years which will be automatically extended for a further 5 years after expiration, will greatly help us to consolidate and increase trade relations with our customers. China is one of the largest importers of castor beans and we are convinced that the quality of the harvest and the significant potential of the 50,000 hectare castor crop means important benefits for our company".
About the company
Acazis AG (Acazis) based in Gilching near Munich, operates in the cultivation and use of castor plants, the production of edible oils, the provision of any related services and the acquisition and management of companies and shareholding in related companies as well as the as the carrying out of Executive Board functions.
Link to the source

Conclusion: 50,000 hectares of castor production is a lot.. if they can get the same yield. In India the yield varies from 500kg/hectare to 1700kg/hectare. The fact is that people see the potential and castor plantations are coming up in Africa, South America, Mexico.. as the saying goes .. more the merrier. Looking forward to Jayant Agro Organics producing higher value added castor derivatives .. maybe India can start import castor seeds!!

Sunday, April 29, 2012

Castor oil Loan Scam 1100Cr detected by Central Vigilance comission

The Central Vigilance Commission has unearthed a large scale fraud committed by a private firm by allegedly misusing Rs 1,100 crore loan taken from different nationalised banks and wrongly claiming its end-use.
CVC officials said the firm was taking loans from various banks with the stipulations that it will be used by farmers of different states for growing and supplying castor seeds.

During  a detailed scrutiny, the Chief Vigilance Officer of Bank of Maharashtra noticed irregularity and found that the firm has perpetrated an alleged fraud of Rs 50 crore. "The matter was brought to the notice of other banks and the Commission which found that the total amount involved in the whole case is Rs 1,100 crore," a CVC official said. He said that a consortium of nine banks have lent to the firm.

"The loan amount has been siphoned off through Village Level Aggregators appointed by the company. The account has become Non-Performing Asset and has been declared as fraud,"  the official said refusing to divulge further information. The Commission advised the banks to ensure that staff accountability be fixed in the case and has asked them to get the case registered with CBI. "The CBI has been directed to register
the case and investigate the matter," he said.An email query on the matter sent to Bank of Maharashtra and other banks did not yield any response.

"It is a serious fraud. The firm has wrongly claimed that the loan amount was being used by the farmers. We are awaiting CBI's preliminary enquiry report on the matter," the official added

Conclusion: This is not good news.. There were no names mentioned but considering the size of Jayant Agro in the castor business it is a cause for concern. hopefully the whole of udeshi family is involved in day to day running of Jayant Agro and will be able to prevent this scam from impacting Jayant Agro. News has been reported in major news papers in April 22,2012 onwards.


Link to news Item: Link1 , Link 2

Monday, April 23, 2012

Jayant Agro: Castor Crop Survey-SEA & Jayant estimated earnings Year 2011-12

Looks like there has been a huge increase in cultivation of Castor in India. As per Solvent Extractors Association (SEA) of India.

=   Total area under Castor crop in India for the year 2011-12 is 11.50 lakh hectares. It has increased by 34% as compared to previous year.

=    Estimated total production of Castor Seeds in India for the year 2011-12 is 16.19 lakh tonnes.  It has increased by 30% as compared to previous year.

=   
Average yield for the year 2011-12 is 1417 kg/hectare as against 1453 kg/hectare during the year 2010-11.  It has decreased by 3% as compared to previous year.


Export numbers have also increased by 60% .. so we can expect Jayant also to report higher earnings for the year ended March 31,2012.

Jayant has reported for 9 months ended dec2011.(Year on Year)Sales increase: 62%  PBDIT Profit margin of 5.05%Net Profit margin of 1.83%

Assuming Jayant Agro maintains the same profit margins as reported for 9 months ended Dec 2011we can expect Jayant Agro Expected year ending March 2012:-Sales:1,875.20crPBDIT: 94.69crNet Profit: 34.31cr EPS: 22.87


Please Note for year ending March 2011 Profit margins were
PBDIT : 5.41%
Net Profit: 2.10%

Assuming Jayant maintains the same margin as march 2011..(higher than margins for 9 months ended dec 2011) these margins would result in :- 
- PBDIT:  101.44cr
- Net Profit: 39.37cr
- EPS: 26.25

Now we all know that Sebacic acid derivatives plant has started production from dec 2011 so we can expect margins to improve for 3 months data..

My guess estimate for Year ending March 2012 Net Profit numbers:
Poor Result would be below 31Cr EPS: 20.66
Fair result would be: 34.31cr EPS: 22.87
Great result would be: 39cr,  EPS: 26 or above

A     whatever the result .. we can expect the dividend payout to increase based on historical figures..  
        dividend payout as percentage of net profit (Including dividend tax):
          March 2011: 13.40%
          March 2010: 23.33%
          March 2009: 36.18%
          March 2008: 25.65%
   
          So even assuming 5 yrs avg of 19.71% and assuming worst case result of 31Cr Net Profit: Dividend payout will be rs 4.07 per share assuming 34-39cr as net profit dividend payout could be: 4.46 - 5.12 assuming 13.4% for net profit of 31cr we can expect dividend of 2.76 (Poor payout) 
C
           Conclusion: Jayant is a strong value buy! For year ending March 2012 we can expect Jayant Agro to report:
            Topline of 1875cr 
            Net Profit from 30cr to 39cr, 
            EPS of 20-26 per share and 
            Dividend payout from Rs 2.76 to 5.12 per share (before dividend tax)

 
       PN: this is my personal view based on publicly available information. please do your own deep dive before investing


Saturday, April 21, 2012

Jayant Agro: Castor oil to rescue Auto Companies..

Here is an interesting article by ICIS Green Chemical Blog

For the benefit of readers I have copied it but here is the link to the original article

The global automotive industry is abuzz with the tightened supply of polyamide 12 (also called nylon 12) which are used in cable ties, wire insulation, flexible hosing, nozzles, damping cogwheels, flexible cover caps, sheet gaskets, sealing rings, and in other fuel line applications/auto-related parts.
PA-12 is also used in plastic parts to make solar panels and cable coverings used in offshore oil and gas production.


Based on several googled websites, PA-12 reportedly have excellent properties such as high degree of dimensional stability under humidity or freezing environment; high resistance to chemicals such as hydraulic fluids, oil, fuels, grease, salt water, solvents; strong resistance to cracking under stress; high-resistance to abrasion; and has high fatigue resistance.
PA-12 also dampens noise and vibration, according to various sources. Unfortunately, I am not familiar with cars but from what I've seen on several news about this PA-12, this is an important chemical for the automobile industry as car makers and several players along the automotive supply chain held an emergency meeting yesterday in Detroit, Michigan, to discuss the critical issue on PA-12 shortage.
According to this article from Plastics News, there are very few suppliers worldwide of  PA-12, namely Evonik, Arkema, Ube Industries and EMS-Grivory. Global PA-12 production was estimated at around 100m lbs/year. Evonik is the only producer here vertically integrated in a key PA-12 feedstock called cyclododecatriene (CDT), which is manufactured by cyclotrimerization of butadiene.
CDT is used to make laurolactam, which in turn is used as a monomer in PA-12.
Unfortunately, a fire broke out at the end of March at Evonik's CDT facility in Marl, Germany, (two employees were killed) and CDT production (capacity is not disclosed) is expected to remain out-of-order for at least three months. This in turn, will affect PA-12 production for those who are dependent on CDT material.
Now here comes the castor part (sorry it took a while to get to this point...).
According to Evonik, the company is able to provide alternative substitutes to its CDT-based PA-12 products in the form of its VESTAMID Terra DD, which contains 45% renewable-based materials made from castor oil derivatives (mostly sebacic acid). The product is based on the polycondensation product of 1,10-decamethylene diamine and 1,12-dodecanedioic acid (this is where sebacic acid comes from).
VESTAMID Terra also comes as polyamide 6,10 which has a 63% biocontent -- the polycondensation of 1,6 hexamamethylene diamine and 1,10 decanedoic diacid (another sebacic acid material); and polyamide 10,10 - a 100% bio-based polymer from the polycondensation of 1,10 decamethylene diamine and 1,10 decanedoic diacid.
Evonik said it is possible to modify the biobased polymers to achieve much of the same material attributes as PA-12. In fact, the company announced yesterday that it has begun measures to increase production capacities of its VESTAMID Terra polymers at its Shanghai, China, plant.
An additional compounding facility for VESTAMID Terra will become operational in the third quarter of this year, and new capacity for the polymerization of the bio-based nylon are in the works and is scheduled to operate in the second half of 2013.
As the blog noted in previous posts about castor-based polyamides, Arkema has also been expanding its castor-based polyamides (under the RILSAN brand) -- when it acquired Hipro Polymers and Casda Biomaterials last year.
Other castor-based polyamides producers include Rhodia (Technyl eXten: PA-6,10) , BASF (Ultramid Balance: PA-6,10),  DSM (EcoPaXX: PA-4,10) and DuPont (Zytel PA-10 and PA-6,10). One thing to note is that Elevance is also targeting to produce natural oil-based derivatives such as diacids for PA-11 and PA-12 and is currently collaborating with companies like Arkema and DSM.
An interesting information about this PA-12 shortage is that other types of polyamides such as PA-6,12 and PA-6,10 could be an alternative to PA-12, according to producers who were interviewed* by ICIS colleagues at the recent plastic tradeshow NPE.
According to US plastic compounder A Schulman, PA-6,12 is a superior alternative to PA-12 for automotive applications given the same chemical resistance factors but PA-6,12 is said to have higher melting point. According to A Schulman, PA-12 supply has been increasingly tight even before the Evonik fire incident as demand from the oil and gas production has taken consumption share from the automotive supply chain.
More plastics are also being used in the automotive manufacture and therefore nylon-based materials are increasingly being used.
DuPont said* it is also working with auto makers to find alternatives for PA-12 in certain applications.
Rhodia, which produces PA-6,10 is reportedly* also working with customers to seek replacement for PA-12, while BASF -- a small CDT supplier as well, is offering its support to PA-12 producers.
Meanwhile, Evonik has also been in the middle of a planned PA-12 expansion, which was announced in December last year. Evonik said a 5,000 tonnes/year PA-12 expansion will supposedly start this year, and another 20,000 tonnes/year PA-12 expansion in its Asian facility is scheduled to be completed within 3 years.

Conclusion: Jayant Agro is the cheapest big Castor oil companies in the heart of castor growing region in the World.
Jayant Sales are approximately Rs 2000Cr ie USD  400 million dollar
Jayant Market Cap is: Rs 155Cr ie USD 31million dollars
Jayant is the largest processor of Castor Seeds are per Solvent Extractors Association (SEA) since 2005 till date (Link)
Banaskantha district in gujarat produces the largest amount of castor seeds ..and jayant has seed crushing plant in banaskantha.. how big is banaskantha? well here is a comparision.. According to castor oil Report (Must download link) 
China production of castor oil:81,400Tonnes
Banaskantha District castor Seed production: 178,240Tonnes (2009-10) Banaskantha oil production is 53,472 - 71,296 tonnes.. standalone Banaskantha district would be 3rd largest producer in the world!! (Seed to oil conversion is 30-40%)
Promoters own 65% equity in Jayant and ITOH Oil 4% .. so still one can buy 30% stake in the largest castor oil player in India for just 9 million Dollars!! 
Jayant promoters have patented production process for efficient production of sebacic acid ... patent is valid till 2020.(Link)
Jayant has been consistently paying dividends each year for the past 18 yrs..(3.5cents per share 2011)
CMP of jayant stock is Rs 103.6 ie USD 2.07 per share. (Calculation is based on conversion rate of Rs 50=1USD)
So here its is Folks if you are not invested in Jayant Agro you are really missing out on one of the best Green chemical stock in the world. With new Indian govt regulations which allow foreign individual investors to directly invest in equity of Indian companies.. Investment opportunity in Jayant agro stock is available to one and All!! .... 9 milion USD will buy you a 30% stake in Jayant Agro Oragnics . Ideal price for Jayant is one times sales ie upside is 10 times current stock price.